
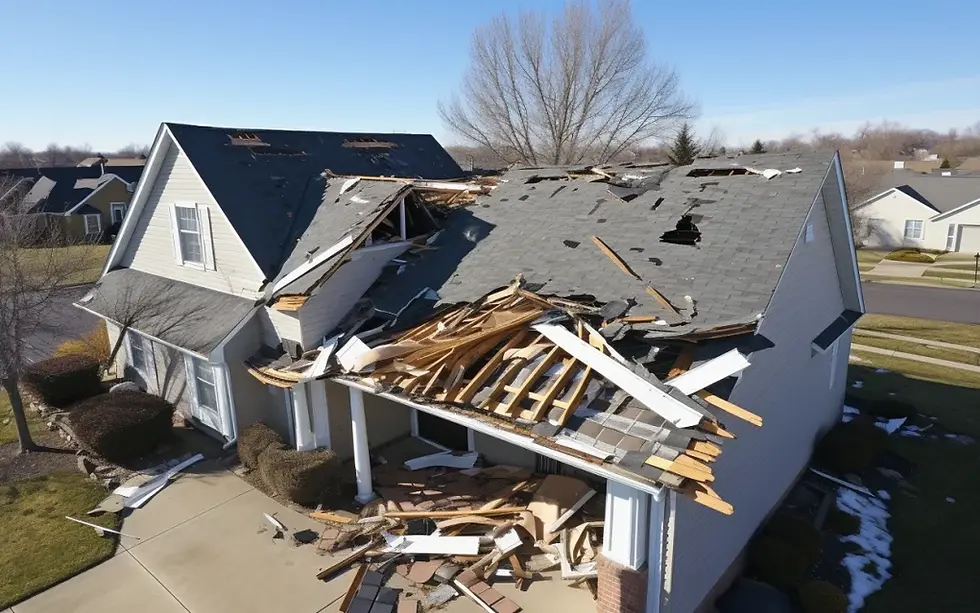


Why Storm Damage Claims Get Underpaid in Boston's Older Homes
A storm claim in Boston is rarely simple. The house may be a Dorchester triple-decker with layered roofing, a South End brownstone with historic trim, or a Somerville two-family with plaster walls, balloon framing, and a roof that has seen decades of freeze-thaw cycles.
When wind, rain, hail, or snow causes damage, the insurance estimate often treats the home like a newer suburban build. That mismatch is one reason Boston-area homeowners see storm damage claims come in lower than the real cost to repair.

Older Boston homes do not fail in simple ways
Many Boston homes were built long before modern roofing systems, ventilation standards, and building codes. That does not make them weak, but it does make storm damage harder to evaluate.
A newer roof assembly is usually more predictable. A storm lifts shingles, water enters at a flashing point, and the repair scope is fairly direct. In older homes, the damage may travel through:
Multiple layers of old roofing
Slate, wood, or older asphalt materials
Chimney flashing that has been patched many times
Box gutters or built-in drainage
Plaster ceilings and horsehair plaster walls
Original trim and nonstandard framing
A wind-driven rain event can enter at the roof, follow old framing, stain a ceiling two rooms away, and leave only subtle evidence at first. If an adjuster writes the claim based only on what is visible from the ground or a quick interior walkthrough, the estimate may miss the true repair path.
That is where underpayment starts. The claim is not always denied. It is often accepted too narrowly.
Triple-deckers create special claim problems
Boston’s triple-deckers are a major part of the region’s housing history. They are also difficult buildings to scope after a storm.
A single roof may protect three separate living spaces. Water may enter the top unit first, then move through wall cavities, back stairwells, electrical chases, or shared structural areas. Damage can show up differently in each unit.
Insurance estimates often miss the way these buildings function as a system. For example, a claim may include a ceiling patch in the third-floor unit but ignore wet insulation, damaged sheathing, or moisture behind shared walls. A lower unit may show delayed staining days later, after the adjuster has already closed the initial inspection.
There is also the issue of access. Steep roof pitches, narrow lots, tight driveways, and closely spaced buildings can make inspection harder. If the roof is not safely inspected up close, lifted shingles, damaged flashing, and soft decking may go undocumented.

Age gets confused with cause
One of the most common reasons storm claims get underpaid is the argument that the damage is simply old wear and tear.
Boston roofs work hard. They face nor’easters, heavy rain, wind gusts, ice, snow loads, humidity, salt air in coastal neighborhoods, and repeated freeze-thaw cycles. Many roofs also have older repairs layered over even older materials.
Insurers can and do account for age. They may apply depreciation. They may exclude long-term deterioration. But age should not erase covered storm damage.
The key question is cause. Did the storm lift shingles, crack slate, damage flashing, force water through an opening, pull gutters away, or knock a tree limb into the roof? If so, the claim should account for the damage caused by that event, even if the home was not new.
Problems arise when an estimate uses broad language such as “old roof,” “deferred maintenance,” or “pre-existing condition” without separating prior wear from new storm impact. That can shrink the scope and leave the homeowner paying for repairs that belong in the claim.
Historic materials cost more to repair correctly
Older Boston homes often contain materials that are not easy to match or replace. Slate roofing, copper flashing, wood windows, built-in gutters, original plaster, decorative molding, and masonry details all require more care than standard modern replacements.
That matters because a low estimate may price the repair as if every material is readily available at a big-box store. A small ceiling patch in a plaster room may require skilled plaster work, not just drywall. A damaged slate roof may need individual tile replacement by a roofer who knows how to handle slate. Historic trim may need custom milling.
The issue is not cosmetic perfection. The issue is whether the estimate reflects a repair that restores the property in a proper and code-compliant way, subject to the policy.
Older homes can also trigger code-related costs. If storm repairs open part of a roof, wall, or electrical area, local requirements may affect what must be brought up to current standards. Coverage for these costs depends on the policy, often under ordinance or law coverage. If that part of the policy is overlooked, the settlement may fall short.

Estimates often miss the hidden parts of the repair
A storm damage estimate is only as good as the inspection behind it. In older homes, the most expensive damage may be hidden until work begins.
Commonly missed items include:
Wet roof decking beneath old shingles
Damp insulation in attic bays
Water behind plaster or lath
Damaged chimney flashing
Separated gutters or downspouts
Interior staining that appears after the first inspection
Matching issues across older exterior materials
Temporary protection needed before permanent repairs
Insurers may also write for spot repairs when full-system repair is more realistic. For example, replacing a few shingles on a brittle, older roof may not be possible without damaging surrounding shingles. Matching can be especially hard when the existing material is weathered, discontinued, or historically specific.
This does not mean every claim deserves a full roof replacement. It does mean the estimate should reflect what a qualified contractor can actually repair in the field.
Documentation makes a major difference
Good documentation is one of the best protections against an underpaid claim. After a storm, the file should tell a clear story: what happened, where the damage is, how water traveled, and what repairs are needed.
Helpful documentation includes:
Photos of the exterior and interior before temporary repairs
Close-up images of roof, flashing, gutter, siding, and chimney damage
Dates and times of the storm and when damage was discovered
Contractor notes explaining storm-related damage
Moisture readings when water intrusion is suspected
Invoices for emergency tarping or mitigation
Photos of hidden damage found during repair work
Do not throw away damaged materials too quickly. If safe and practical, keep samples or photograph them clearly before disposal. If temporary repairs are needed to prevent more damage, document them first.
A second inspection can also help when the first estimate seems too low. Older Boston homes need inspectors and contractors who understand local construction, not just generic pricing software.

What to watch for in a low storm claim estimate
A low estimate is not always wrong, but certain signs should raise concern.
Look closely if the estimate:
Lists only interior paint and ignores the exterior entry point
Prices drywall repairs in rooms with original plaster
Mentions age but does not explain the storm damage analysis
Leaves out roof access, steep slope, or difficult staging
Ignores chimney, flashing, gutter, or drainage details
Applies heavy depreciation without clear support
Omits code-related work that may be required
Closes the claim before delayed water damage appears
This is especially true in older homes where opening the damaged area can reveal more than the first inspection showed. Supplemental claims exist for that reason. The first estimate should not be treated as the final word if new storm-related damage appears during repairs.
This article is for general information only and is not legal, insurance, or financial advice. Policy language, coverage, and claim rights vary.
The real reason claims get underpaid
Storm claims in older Boston homes get underpaid because the damage is easy to oversimplify. A triple-decker is not a new townhouse. A slate roof is not a standard shingle roof. A plaster ceiling is not a piece of drywall. Historic construction, tight urban lots, old materials, and hidden water paths all change the cost and scope of repair.
The strongest claim connects the storm to the damage with clear evidence, local construction knowledge, and repair estimates that reflect the home as it actually exists.
The takeaway is simple: when an older Boston home suffers storm damage, do not rely on a quick surface-level estimate. Document everything, ask careful questions, and make sure the repair scope matches the building, not a generic version of it.


Comments