top of page

Expert Public Adjusting, and claims consultation backed by the CPCU Credential. The CPCU designation (Chartered Property Casualty Underwriter) is the highest and most respected credential in the property insurance industry. It represents advanced, graduate‑level mastery of insurance coverage, claims handling, risk analysis, and ethics. Very few adjusters earn it — and even fewer Public Adjusters hold the credential.
 

As a CPCU‑certified Public Adjuster, I bring expert‑level understanding of how insurance companies evaluate claims, interpret policy language, and calculate settlements. This means your claim is prepared, documented, and presented with the same precision carriers use internally.
 

I don’t rely on guesswork or generic templates. I apply proven, industry‑standard methods to ensure every detail of your loss is captured and supported. My CPCU training reinforces a strict ethical code focused on protecting policyholders and advocating for fair, accurate settlements.

When you work with me, you’re working with the CPCU standard — the highest level of knowledge, ethics, and professionalism in the claims industry.

OIP (1).jpg
fixd-blog-77-1080x675.webp
ai-generated-waterfront-homes-in-a-row-on-the-water-with-reflection-of-sky-3d-rendering-of

When you suffer property damage in Maine., you deserve someone who works for you—not the insurance company. As a CPCU‑certified Maine Adjuster, I help homeowners and businesses turn complex losses into clear, fair outcomes. I document every detail, interpret your policy, negotiate on your behalf, and make sure your settlement reflects the true scope of your damage. My mission is simple: protect policyholders, eliminate confusion, and bring integrity, strategy, and clarity to every claim. After years of paying premiums, you deserve a professional who ensures your insurance finally works the way it should.

Alfred Smith CPCU Claims Services LLC

Helping families and businesses recover after loss — a regional adjuster bringing strategic claims leadership and CPCU-certified advocacy to every case.

Ice_dam_slate_roof-scaled-1.jpg

Our Services

01

Residential Claims

We provide expert advocacy for residential property claims, ensuring your home is valued accurately and your insurance settlement reflects the full extent of your loss. Your home, your belongings, and your additional living expenses are all essential parts of your claim, and we make sure nothing is overlooked or

underpaid.

02

Commercial Claims

We provide specialized support for commercial and industrial property claims, ensuring your building, business personal property, and loss of business income are fully recognized and accurately valued. Commercial losses affect more than the structure — they impact operations, inventory, equipment, and your ability to generate revenue.

Our assessments focus on the complete scope of your commercial loss so your insurance recovery reflects the true financial impact on your business. After years of paying premiums, it’s time for your insurance to pay what your policy promises.

03

Settlement Advocacy

If you’ve been underpaid or your claim wasn’t handled properly, you deserve a second look. We represent your interests throughout the entire claims process, ensuring every detail is documented, supported, and included in your pursuit of a fair and just settlement. Your policy has protections, your loss has value, and your claim deserves to be paid accurately.

Let me work for you — and make sure your settlement reflects the full extent of your damage.

Frequently asked questions

CPCU, AIC, AIM, ARM, Haag Certified Inspector

Licensed Public Adjuster in Massachusetts, Rhode Island and Connecticut · Licensed Adjuster in Maine

Insurance Claim Denied or Underpaid? We Fight for You

20261026_195421006_iOS.png

Your Insurance Advocate for Large and Complex Losses

Catastrophic Loss? Get a Professional on Your Side from Day One

Maine claims we handle

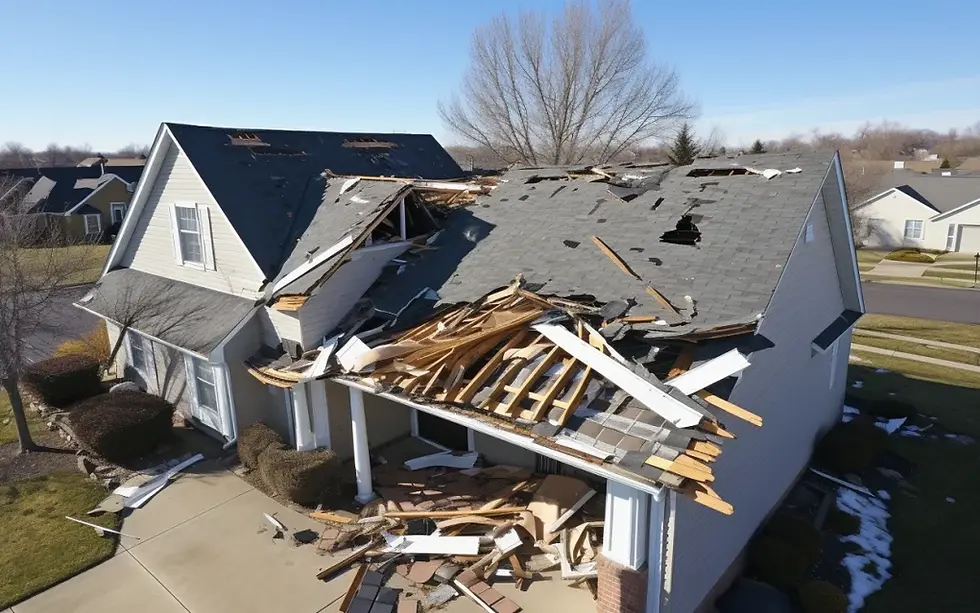
  • Snow load and roof collapse. Heavy, wet snow and layered ice can overload older roofs, barns, garages and low-slope additions. Whether it counts as a covered collapse often comes down to documentation and policy wording.

  • Ice dams. Water backing up under shingles and into ceilings and walls, a common winter loss across Maine.

  • Frozen and burst pipes. Especially at seasonal homes and camps, where vacancy and heat-maintained conditions in the policy can limit coverage.

  • Wind, nor'easters and coastal storms. Roof, siding and tree damage, and the wind-versus-flood disputes that follow coastal storms.

  • Fire and smoke. Structure, contents and additional living expense while you're out of your home.

  • Commercial property. Building damage, business personal property, and extra expense after a loss.

What we do on your claim

  • Review your policy and explain what it covers

  • Inspect and document all of the damage, including what's hidden

  • Prepare a complete, independent estimate of the loss

  • Present the claim to your insurer and negotiate the settlement

  • Handle the supplements, reinspections and paperwork so you don't have to

Your rights under Maine law

  • An adjuster must wait at least 36 hours after a loss before offering you a contract for services.

  • You can cancel a public adjusting contract within 2 business days after signing it. That notice must be printed prominently on the first page of the contract.

  • Fees must be reasonable for the services provided.

Talk to us before you accept the insurance company's offer

Book a free 20-minute claim consultation, or fill out our Free Claim Review form and Alfred will contact you.

Phone: 617-697-2646 Email: alfredsmithcpcu@gmail.com

The “Do-It-Myself” Insurance Claim: A Funny Story With a Not-So-Funny Lesson

alfredsmithcpcu
Aug 9
2 min read
Do it yourself claims!! Beware.

Every homeowner thinks they can handle an insurance claim on their own… until they actually try to handle an insurance claim on their own.

Here’s a lighthearted story about one Massachusetts homeowner who learned—very quickly—why not hiring a CPCU public adjuster can put you in a less‑than‑favorable position.


Meet Bob.

Bob is a good guy. Bob is handy. Bob once fixed a leaky faucet using a YouTube video from 2011.

So when a pipe burst in his basement, Bob said the five words that have doomed homeowners since the beginning of time:

“I can handle this myself.”

Stage 1: The Phone Call

The phone call to the carrier.

Bob called his insurance company and confidently explained the situation.

Except… Bob forgot a few details. Like the part where the water ran for three hours. And the part where it soaked the drywall. And the part where it traveled under the flooring into the laundry room.

Bob told the insurer: “Yeah, it’s just a little water.”

The adjuster wrote down: “Minor water damage.”

You can see where this is going.


Stage 2: The Inspection

The insurance adjuster arrived. Bob tried to show the damage, but he didn’t take photos, didn’t save receipts, and didn’t move anything out of the way.

The adjuster looked around and said, “Well, I don’t see much.”

Bob said, “Yeah, it dried.”

The adjuster said, “Great.”

Bob said, “…Wait.”

Angry Bob played by Burt

Stage 3: The Estimate

Insurance adjuster without Bob hiring a public adjuster

Bob received the estimate. It covered:

  • One piece of drywall

  • A small section of flooring

  • A “quick cleanup”

Bob stared at the number. Bob blinked. Bob blinked again.

Bob said, “This won’t even cover the shop vac I had to buy.”


Stage 4: The Contractor Visit

Bob's Contractor
Bob's Contractor

Bob’s contractor arrived, took one look, and said the words every homeowner dreads:

“Yeah… this is way worse than the insurance estimate.”

Turns out the water traveled into:

  • The wall cavity

  • The insulation

  • The electrical outlet

  • The laundry room

  • The hallway

  • And somehow, mysteriously, the coat closet

Bob asked, “How did it get into the coat closet?”

The contractor shrugged. “Water is sneaky.”

Stage 5: The Realization

Duh, I should have known.

Bob sat at his kitchen table, surrounded by:

  • A lowball estimate

  • A contractor quote triple the amount

  • A stack of receipts

  • A wet‑vac

  • And a growing sense of regret

Bob finally said the words he should’ve said on Day One:

“I should’ve hired a public adjuster.”


Where Alfred Smith CPCU Claims Services LLC Comes In


Alfred Smith CPCU Claims Services LLC

A CPCU public adjuster would have:

  • Documented all the damage

  • Explained the loss correctly

  • Identified hidden water migration

  • Managed the inspection

  • Negotiated the scope

  • Ensured the estimate matched the real repairs

  • Prevented Bob from becoming a cautionary tale

Instead, Bob became a blog post.


The Lesson

Insurance claims aren’t DIY projects. They’re not like fixing a faucet or hanging a shelf. They’re complex, technical, and full of pitfalls that homeowners don’t see coming.

Hiring a CPCU public adjuster—especially early—keeps you out of the “Bob situation” and ensures your claim is handled correctly from the start.


Don't Be like Bob


Don't be like Bob. Hire a CPCU Public Adjuster


Comments


bottom of page