top of page

Expert Public Adjusting, and claims consultation backed by the CPCU Credential. The CPCU designation (Chartered Property Casualty Underwriter) is the highest and most respected credential in the property insurance industry. It represents advanced, graduate‑level mastery of insurance coverage, claims handling, risk analysis, and ethics. Very few adjusters earn it — and even fewer Public Adjusters hold the credential.
 

As a CPCU‑certified Public Adjuster, I bring expert‑level understanding of how insurance companies evaluate claims, interpret policy language, and calculate settlements. This means your claim is prepared, documented, and presented with the same precision carriers use internally.
 

I don’t rely on guesswork or generic templates. I apply proven, industry‑standard methods to ensure every detail of your loss is captured and supported. My CPCU training reinforces a strict ethical code focused on protecting policyholders and advocating for fair, accurate settlements.

When you work with me, you’re working with the CPCU standard — the highest level of knowledge, ethics, and professionalism in the claims industry.

OIP (1).jpg
fixd-blog-77-1080x675.webp
ai-generated-waterfront-homes-in-a-row-on-the-water-with-reflection-of-sky-3d-rendering-of

When you suffer property damage in Maine., you deserve someone who works for you—not the insurance company. As a CPCU‑certified Maine Adjuster, I help homeowners and businesses turn complex losses into clear, fair outcomes. I document every detail, interpret your policy, negotiate on your behalf, and make sure your settlement reflects the true scope of your damage. My mission is simple: protect policyholders, eliminate confusion, and bring integrity, strategy, and clarity to every claim. After years of paying premiums, you deserve a professional who ensures your insurance finally works the way it should.

Alfred Smith CPCU Claims Services LLC

Helping families and businesses recover after loss — a regional adjuster bringing strategic claims leadership and CPCU-certified advocacy to every case.

Ice_dam_slate_roof-scaled-1.jpg

Our Services

01

Residential Claims

We provide expert advocacy for residential property claims, ensuring your home is valued accurately and your insurance settlement reflects the full extent of your loss. Your home, your belongings, and your additional living expenses are all essential parts of your claim, and we make sure nothing is overlooked or

underpaid.

02

Commercial Claims

We provide specialized support for commercial and industrial property claims, ensuring your building, business personal property, and loss of business income are fully recognized and accurately valued. Commercial losses affect more than the structure — they impact operations, inventory, equipment, and your ability to generate revenue.

Our assessments focus on the complete scope of your commercial loss so your insurance recovery reflects the true financial impact on your business. After years of paying premiums, it’s time for your insurance to pay what your policy promises.

03

Settlement Advocacy

If you’ve been underpaid or your claim wasn’t handled properly, you deserve a second look. We represent your interests throughout the entire claims process, ensuring every detail is documented, supported, and included in your pursuit of a fair and just settlement. Your policy has protections, your loss has value, and your claim deserves to be paid accurately.

Let me work for you — and make sure your settlement reflects the full extent of your damage.

Frequently asked questions

CPCU, AIC, AIM, ARM, Haag Certified Inspector

Licensed Public Adjuster in Massachusetts, Rhode Island and Connecticut · Licensed Adjuster in Maine

Insurance Claim Denied or Underpaid? We Fight for You

20261026_195421006_iOS.png

Your Insurance Advocate for Large and Complex Losses

Catastrophic Loss? Get a Professional on Your Side from Day One

Maine claims we handle

  • Snow load and roof collapse. Heavy, wet snow and layered ice can overload older roofs, barns, garages and low-slope additions. Whether it counts as a covered collapse often comes down to documentation and policy wording.

  • Ice dams. Water backing up under shingles and into ceilings and walls, a common winter loss across Maine.

  • Frozen and burst pipes. Especially at seasonal homes and camps, where vacancy and heat-maintained conditions in the policy can limit coverage.

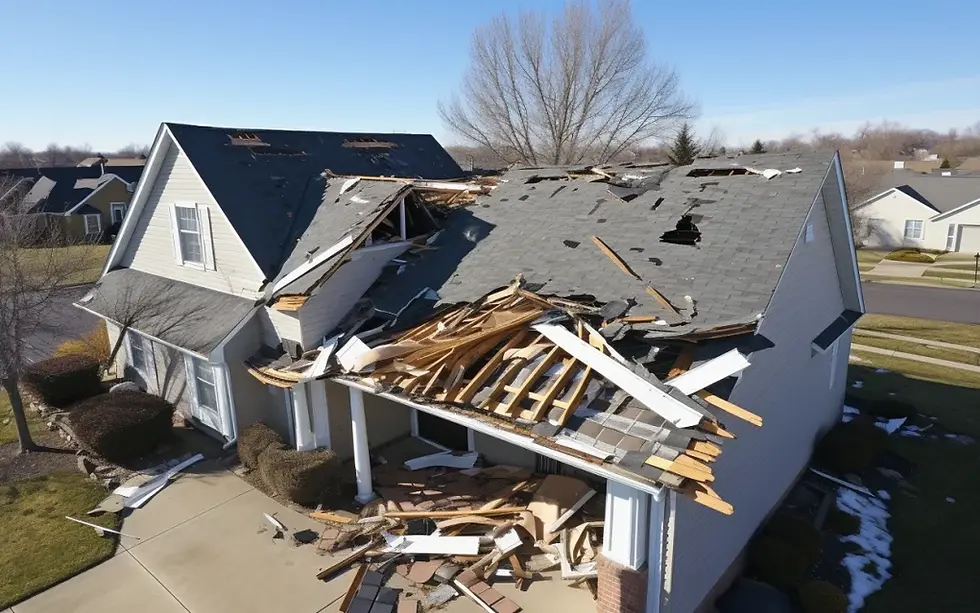
  • Wind, nor'easters and coastal storms. Roof, siding and tree damage, and the wind-versus-flood disputes that follow coastal storms.

  • Fire and smoke. Structure, contents and additional living expense while you're out of your home.

  • Commercial property. Building damage, business personal property, and extra expense after a loss.

What we do on your claim

  • Review your policy and explain what it covers

  • Inspect and document all of the damage, including what's hidden

  • Prepare a complete, independent estimate of the loss

  • Present the claim to your insurer and negotiate the settlement

  • Handle the supplements, reinspections and paperwork so you don't have to

Your rights under Maine law

  • An adjuster must wait at least 36 hours after a loss before offering you a contract for services.

  • You can cancel a public adjusting contract within 2 business days after signing it. That notice must be printed prominently on the first page of the contract.

  • Fees must be reasonable for the services provided.

Talk to us before you accept the insurance company's offer

Book a free 20-minute claim consultation, or fill out our Free Claim Review form and Alfred will contact you.

Phone: 617-697-2646 Email: alfredsmithcpcu@gmail.com

The Truth About Insurance Company Adjusters vs Public Adjusters

alfredsmithcpcu
Jul 17
2 min read

When property damage strikes, most homeowners assume their insurance company will guide them through the claim process fairly. But the truth is simple: insurance company adjusters work for the insurance company — not for you.   Public adjusters, on the other hand, represent you, the policyholder, and fight to secure the maximum payout you’re entitled to.

Understanding the difference can be the key to protecting your home, your business, and your financial recovery.

Insurance Company Adjusters: Who They Really Work For

Insurance company adjusters are employees or contractors hired by the insurer. Their job is to:

  • Evaluate your damage

  • Interpret your policy

  • Estimate repair costs

  • Protect the insurance company’s financial interests

Even when they seem friendly or helpful, their responsibility is to minimize the claim payout and close the file quickly.

Common tactics used by insurance company adjusters

  • Underestimating repair costs

  • Overlooking hidden damage

  • Using preferred vendors who underbid

  • Delaying communication

  • Pressuring homeowners to accept low offers

  • Misinterpreting policy language in the insurer’s favor

They’re not “bad people” — they’re simply doing the job they’re paid to do.

Public Adjusters: Your Advocate in the Claims Process

A public adjuster works exclusively for you, not the insurance company. Their job is to:

  • Document all damage thoroughly

  • Interpret your policy correctly

  • Prepare a detailed claim

  • Negotiate with the insurance company

  • Fight for the highest possible settlement

Public adjusters level the playing field and ensure you’re not taken advantage of during a stressful time.

What a public adjuster does for you

  • Conducts a full inspection of your property

  • Identifies hidden or overlooked damage

  • Creates a professional estimate

  • Handles all communication with the insurer

  • Challenges lowball offers

  • Ensures you receive every dollar you’re owed

Most homeowners don’t realize how much money they leave on the table without a public adjuster.

Key Differences at a Glance

Insurance Company Adjuster

  • Works for the insurance company

  • Protects the insurer’s bottom line

  • Minimizes payouts

  • May rush or undervalue the claim

  • Represents the insurer’s interests

Public Adjuster

  • Works for YOU

  • Protects your financial recovery

  • Maximizes payouts

  • Documents everything thoroughly

  • Represents your interests

Why This Matters for Homeowners and Businesses

Property damage is expensive — and insurance companies often try to pay as little as possible.

Hiring a public adjuster can:

  • Increase your payout

  • Reduce stress

  • Save time

  • Prevent mistakes

  • Ensure fair treatment

  • Protect your rights as a policyholder

Most homeowners don’t know their claim can be tens of thousands of dollars higher when handled by a public adjuster.

When Should You Hire a Public Adjuster?

You should consider hiring a public adjuster when:

  • Your claim feels overwhelming

  • The insurance company is delaying

  • You received a low offer

  • You suspect damage was overlooked

  • You’re dealing with fire, water, storm, or mold damage

  • You want a professional handling everything

If you’re unsure, a public adjuster can review your situation and tell you whether you’re being treated fairly.

Final Thoughts

Insurance company adjusters protect the insurer. Public adjusters protect you.

If you want a fair, accurate, and fully maximized claim, hiring a public adjuster is one of the smartest decisions you can make.


Comments


bottom of page