


Why Homeowners Shouldnt Go It Alone After a Claim Denial
By Alfred Smith, CPCU | Alfred Smith CPCU Claims Services LLC
A claim denial can feel final when it lands in your mailbox. It is not always final.
I spent more than 25 years on the carrier side of the claims business. I know how insurance companies are set up to handle a loss, because I used to do it for them. I know how files get reviewed, how estimates get questioned, how coverage positions get written, and how easily a homeowner can be left trying to answer a complicated insurance argument without the same tools the carrier has.
Now I work for the policyholder.
The last few weeks on my claim files are a good reminder of why that matters. I am seeing estimates that shrink without explanation. I am seeing denial letters that change once they are challenged. I am seeing carriers rely on broad policy language while refusing to come back out and look again.
This article is for general information only. It is not legal advice. Claim rules and dispute procedures vary by state, policy, and facts.

The estimate that shrank without a clear explanation
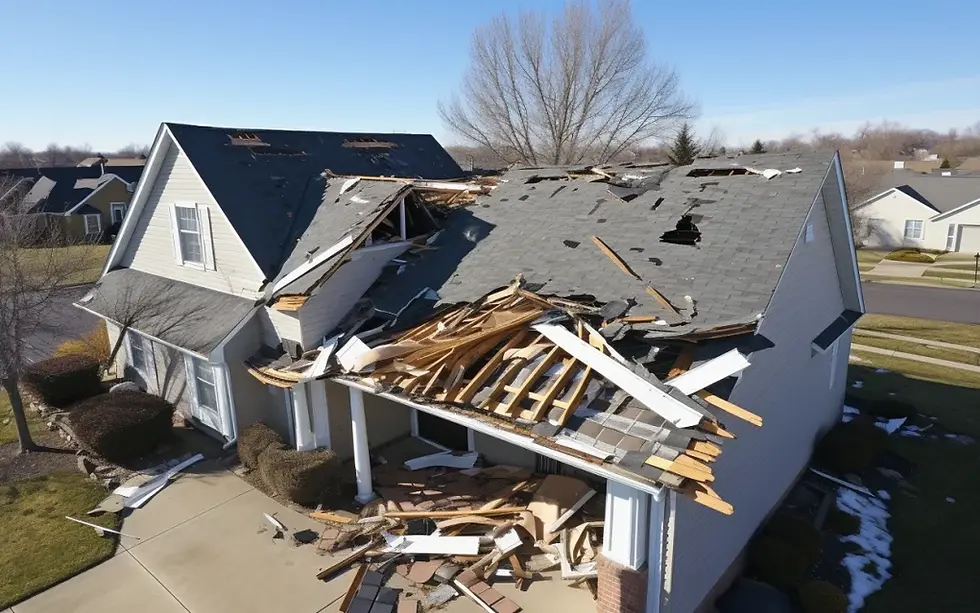
On one recent file, a vehicle hit a home.
The carrier sent out its own contractor. That contractor put the repair at about $42,000. Then the number the carrier actually wanted to pay came in much lower.
Nobody explained the gap.
That matters. A homeowner cannot fairly respond to a claim payment if the carrier does not show how it got there. Was the scope reduced? Were materials changed? Were labor charges cut? Did the carrier remove code items, structural work, temporary protection, or other necessary repairs?
Those details are not minor. They are the claim.
When a carrier’s contractor gives one number and the carrier’s payment position lands far below it, the policyholder should not be expected to guess what changed. The estimate should be available line by line.
How I handled it
I sent a written request for the carrier’s full estimate, line by line.
That is the starting point. You cannot fight a number you have not seen. You need to know what the carrier included, what it left out, and what assumptions it made.
When the carrier did not move, I took the file to a Massachusetts reference hearing. That is the state’s formal process for settling disputes over the amount of a loss.
A reference hearing is not something most homeowners deal with in everyday life. It has rules. It requires preparation. It requires evidence, documentation, and a clear presentation of the disputed amount.
That is exactly where experience matters.
A homeowner may know the damage is real. A contractor may know the repair will cost more than the carrier offered. But the claim still has to be presented in a way that answers the insurance company’s position and fits the dispute process.
The lesson from that file
The first number is not always the final number.
The carrier’s contractor works for the carrier. That does not automatically mean the estimate is wrong, but it does mean the homeowner should not treat it as neutral advice. The carrier controls what it accepts, what it questions, and what it pays.
A homeowner is entitled to ask:
What estimate did the carrier rely on?
What line items were included?
What line items were removed?
Who made the changes?
What policy language supports the reduction?
What dispute process applies if the parties cannot agree?
Those are not aggressive questions. They are basic claim questions.
The denial that kept changing
Another homeowner had water coming in through failed roof flashing on a fairly new roof.
The carrier denied the claim under the water damage exclusion. I pushed back in writing. Then the carrier’s reason changed.
Then it changed again.
After that, the carrier added a long-term rot argument that was not in the original denial. It also refused to send anyone back out to look.
That kind of shifting position is a warning sign.
A denial letter should explain the carrier’s position based on the facts, the policy, and the investigation. If the reason keeps changing after the denial is challenged, the homeowner should slow the process down and make the carrier put its position in writing.
Do not rely on phone calls alone. A phone call can be helpful, but it does not create the same record as a written response.
How I handled it
I answered every new position in writing.
When the carrier raised the water damage exclusion, I answered that issue. When the reason changed, I answered the new issue. When the carrier added the long-term rot argument, I addressed that too.
I also put on record that the carrier had declined to reinspect the property.
That point matters. If a carrier takes a new position but refuses to look again, the file should reflect that. A homeowner may later need to show that the carrier had the chance to investigate further and chose not to.
The claim has since been resolved.
The lesson from that file
A denial letter is not always the end of the claim.
Sometimes it is the start of the real claim dispute.
When the carrier’s reasons keep changing, that tells you something. It may mean the original denial was not as strong as it looked. It may mean the facts were not fully developed. It may mean the adjuster is trying to fit the damage into an exclusion after the fact.
The way to deal with that is to build a paper trail.
A good paper trail does several things:
Confirms what the carrier said
Locks in dates and positions
Shows what documents were requested
Shows what inspections were refused
Preserves the policyholder’s right to challenge the denial
If it is not in the file, it may as well not have happened.
That is one of the first lessons I learned on the carrier side. It is even more important for policyholders.

Why the carrier has the advantage from the start
Insurance companies handle claims every day. Most homeowners do not.
That difference shows up quickly after a loss. The carrier has adjusters, supervisors, estimators, engineers, contractors, coverage consultants, and claim systems. The homeowner usually has damage, stress, repair decisions, and a policy full of terms they may never have read closely before.
That is not a fair match.
The claim process may look simple from the outside. Report the loss, meet the adjuster, get the estimate, receive payment, make repairs. But once there is a dispute, it changes.
The questions become more technical:
Was the damage sudden or long term?
Does an exclusion apply?
Is there an exception to the exclusion?
What part of the damage is covered?
What part of the repair is needed to restore the property?
Did the carrier consider all available information?
Did the carrier explain its position clearly enough?
What deadlines apply?
Those questions can change the outcome of a claim.
A homeowner may be completely honest and still lose ground because they do not know what to ask for or how to respond. That is one reason Why Homeowners Shouldnt Go It Alone After a Claim Denial is more than a headline. It is a practical warning.
What homeowners should do when a claim is denied or underpaid
A denial or low payment should trigger a careful response, not panic.
The first mistake is accepting the carrier’s position without reviewing it. The second mistake is arguing by phone without creating a written record. The third mistake is waiting too long.
Here is what I would want a homeowner to do early.
Read the denial letter carefully
Do not skim it.
Look for the specific reason the carrier gives. The letter should identify the policy language the carrier relies on and connect that language to the facts of the loss.
Pay attention to whether the letter explains the decision or simply quotes broad policy language. A denial should be more than a policy excerpt.
Ask for the full estimate and claim documents
If the dispute involves the amount of the loss, ask for the estimate line by line.
A summary payment letter is not enough. You need to see the quantities, unit prices, materials, labor, depreciation, and any items removed or reduced.
If the carrier relied on a contractor, engineer, or specialist, ask for the report or basis for the decision.
Put disagreements in writing
A written response does not need to be long, but it should be clear.
State what you disagree with. Identify missing facts. Ask specific questions. Attach supporting documents when available. Keep a copy of everything.
A short written response is often better than a long emotional one.
Do not let a shifting denial go unanswered
If the carrier changes its reason, answer the new reason.
If the carrier adds a new exclusion, ask why it was not included before. If the carrier refuses to reinspect, confirm that in writing.
The goal is not to argue for the sake of arguing. The goal is to make the file accurate.
Get experienced help before the file gets boxed in
Many homeowners wait until the claim is a mess before asking for help.
By then, months may have passed. Repairs may have started. Damaged materials may be gone. Deadlines may be closer. The carrier may have taken several written positions that now need to be untangled.
Getting help early can change the direction of the file.
What I look for when I review a disputed claim
When I review a claim denial or underpayment, I am not only looking at the damage. I am looking at the claim handling.
That includes the policy, the facts, the estimate, the letters, the inspection notes, and the sequence of events.
I want to know what the carrier knew, when it knew it, and how it used that information.
Some of the questions I ask are simple:
Did the carrier inspect the right areas?
Did the carrier speak with the right people?
Did the estimate match the visible damage?
Did the denial letter match the facts?
Did the carrier rely on an exclusion without addressing an exception?
Did the carrier change positions after being challenged?
Did the carrier refuse to reinspect when new information was presented?
This is where my years on the carrier side help. I know what a complete claim file should look like. I know when a position is well supported. I also know when a position looks thin.
That does not mean every denial is wrong. Some claims are denied for valid reasons. Some damages are excluded. Some disputes are really about maintenance, wear, or unrelated conditions.
But when a claim has coverage, the policyholder should not be shortchanged because the carrier wrote the first estimate or issued the first denial.
The homeowner’s biggest disadvantage is not knowing the process
Most homeowners focus on the damage. That makes sense. A damaged home disrupts everything.
The carrier focuses on the claim file.
That difference matters.
The claim file is where decisions get made and defended. It is where estimates, photos, reports, letters, emails, and policy language come together. If the file only contains the carrier’s version of events, the carrier’s version becomes the easiest one to rely on.
The homeowner has to get their evidence into the file.
That may include:
Photos taken before temporary repairs
Contractor estimates with clear scopes of work
Weather information when relevant
Invoices and receipts
Maintenance records
Written explanations from tradespeople
Requests for reinspection
Written objections to incorrect statements
A strong claim is not built on frustration. It is built on proof.
The main takeaway from my files right now
Here is what these recent files show.
A carrier estimate can shrink. A denial can change. A claim that appears closed can still have issues worth challenging. The homeowner who accepts the first answer may leave real money on the table or give up rights they did not know they had.
The answer is not to assume every insurance company is acting in bad faith. The answer is to recognize the process for what it is.
Insurance companies know the process. They work inside it every day.
Homeowners usually enter it under stress, after damage has already happened, and with no reason to know the rules until they are already in the middle of the dispute.
That is why going it alone after a denial or underpayment is risky.
If a claim has been denied, reduced, or explained in a way that does not make sense, slow down. Ask for the documents. Keep everything in writing. Challenge shifting explanations. Get help before the file is boxed in.
The first answer from the carrier may be important, but it is not always the last word.

Alfred Smith CPCU Claims Services LLC
150 Quequechan Rd
Taunton, MA 02780
617 697 2646


Comments