


Preparing for Ice Dam Winter: What to Document Before the First Freeze
Late October is the quiet window before winter starts testing the roof, gutters, attic, and insurance policy all at once.
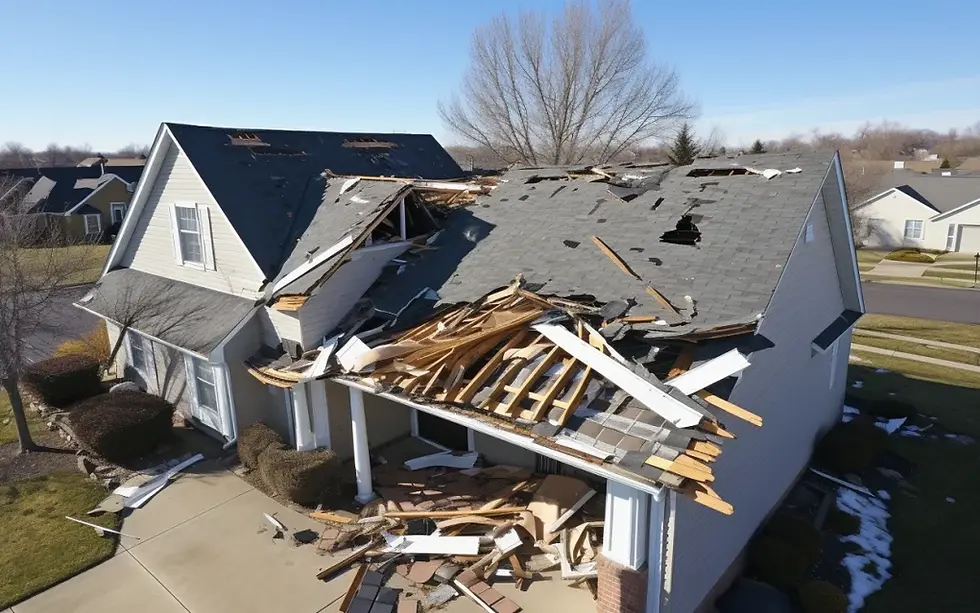
That window matters more in years when winter is expected to swing between thaw, rain, freezing rain, and hard freezes. Intact recently warned that an El Niño winter could bring more ice storm claims. While every region will see different weather, the pattern behind many claims is familiar: snow melts, water runs down the roof, it refreezes at the colder edge, and an ice dam starts pushing water where it does not belong.
The damage may show up as a ceiling stain in January, but the conditions that make a claim easier to understand are often visible before the first freeze. Photos, receipts, inspection notes, and simple maintenance records can help show the condition of the home before winter. They can also help distinguish a sudden water intrusion from a long-running maintenance issue.
This article is for general information only. Insurance coverage varies by policy, state, carrier, and the facts of the loss.

Why ice dams become water intrusion problems
An ice dam is not just a frozen ridge at the edge of a roof. It is a sign that heat, snow, drainage, and freezing temperatures are working against the home.
The basic chain looks like this:
Heat escapes into the attic or upper roof area.
Snow on the warmer part of the roof melts.
Meltwater runs down toward the eaves.
The roof edge is colder, so the water refreezes.
Ice builds up and blocks more meltwater.
Water backs up under shingles or through vulnerable roof details.
Shingles shed water that flows downward. They are not designed to act like a waterproof bathtub when water pools and pushes uphill. Once backed-up water finds a path, it can enter through nail holes, flashing gaps, roof penetrations, or weak underlayment.
Inside the home, ice-dam water intrusion can look like:
Brown or yellow stains near exterior walls
Peeling paint or bubbling drywall
Damp insulation in the attic
Water dripping from window trim
Moisture around recessed lights
Musty odors after freeze-thaw cycles
Stains that appear after a warm day following snow
The tricky part is timing. The ice dam may form over several days, but the visible damage may seem sudden. That distinction can matter when documenting a claim.
The difference between gradual leaks and sudden damage
Insurance policies often treat water damage differently depending on how it happened. The exact wording matters, but many policies draw a line between sudden and accidental damage and gradual, repeated, or maintenance-related damage.
That line is not always obvious from the stain on the ceiling.
Sudden damage often has a clear event
Sudden damage usually involves a specific incident or short time frame. With ice dams, that might be water entering after a major snowstorm followed by a thaw and refreeze. The homeowner may notice active dripping, a new stain, or wet drywall shortly after the weather event.
Examples may include:
A new ceiling stain appearing after several inches of snow and a rapid thaw
Water dripping from a light fixture during an ice dam event
Wet insulation below a roof edge after a freeze-thaw cycle
A visible ridge of ice at the eaves with indoor moisture directly below it
The key is that the damage appears tied to a recent condition, not months or years of neglected maintenance.
Gradual leaks point to long-term conditions
A gradual leak usually suggests repeated water entry over time. Insurers may look for signs that the issue existed before the storm or developed because of deferred maintenance.
Possible signs of a gradual issue include:
Old staining beneath new staining
Rot, mold, or deteriorated wood
Multiple paint layers bubbling in the same area
Long-term gutter overflow marks
Damaged or missing shingles that were not repaired
Attic ventilation or insulation defects that were known but ignored
A gradual leak does not always mean there is no coverage for anything. It does mean the claim may face closer review. Photos and records from before winter can help show what was new, what was maintained, and what changed after the storm.
Weather timing can support the story
A simple weather timeline can help. You do not need to be a meteorologist. Keep basic notes when winter conditions become serious:
Date of heavy snowfall
Date of freezing rain or ice accumulation
Date of thaw or above-freezing temperatures
Date water was first noticed indoors
Date mitigation began
Date a roofer, contractor, or adjuster inspected the damage
These notes can help connect visible damage to a specific event. They are also useful when memories blur after several storms.
What to document before the first freeze
October and early November are ideal times to make a simple home condition record. The goal is not to create a perfect legal file. The goal is to capture clear evidence of the home’s condition before winter weather complicates the picture.
Photograph the roof from safe angles
Do not climb onto a roof unless you have the right training and equipment. Most homeowners can document enough from the ground.
Take photos of:
Each side of the roof
Roof valleys where snow and water collect
Eaves and overhangs
Areas above past ceiling stains
Chimneys, skylights, vents, and other roof penetrations
Missing, curled, or damaged shingles
Tree branches touching or overhanging the roof
Use daylight. Step back far enough to show context, then take closer photos of specific details. If possible, include a date stamp through your phone settings or keep the original image metadata.
Record gutter and downspout condition
Gutters play a major role in winter water problems. Clogged gutters can hold water, add weight, and worsen ice buildup.
Document:
Clean gutters after leaves are removed
Downspouts draining away from the foundation
Loose or sagging gutter sections
Ice-prone corners from past winters
Splash blocks or extensions in place
Any professional gutter cleaning receipt
A photo of clean gutters in late October can be useful if ice forms in January. It helps show that debris was not the obvious cause of water backing up.
Check the attic before it is freezing
The attic often tells the truth before the living space does. If it is safe and accessible, document the condition before winter.
Look for:
Dark roof sheathing
Rusted nails
Compressed or uneven insulation
Bathroom fans venting into the attic
Blocked soffit vents
Gaps around pipes, ducts, or wiring
Daylight through roof openings
Old water stains
Take photos without disturbing insulation more than needed. If you see active moisture, damaged wiring, or unsafe access conditions, stop and call a qualified professional.
The attic also helps explain why ice dams form. Warm air escaping from the living space can heat the underside of the roof. Poor ventilation can trap that warmth. Together, those conditions can melt snow unevenly and feed ice at the eaves.
Save maintenance and repair records
Paperwork matters because it gives dates, names, and scope of work. Save digital copies in one folder.
Useful records include:
Roof repair invoices
Gutter cleaning receipts
Attic insulation work
Ventilation upgrades
Chimney flashing repairs
Tree trimming receipts
Home inspection reports
Contractor estimates
Photos from past projects
If you do your own maintenance, keep a short log. A simple note is better than relying on memory.
Example:
October 24: Cleaned front and rear gutters, checked downspout extensions, photographed roof edges and attic above north bedroom.
That kind of note can be surprisingly helpful later.

A practical pre-freeze documentation checklist
Use this checklist before the first hard freeze. It should take less than an afternoon for most homes.
Area | What to document | Why it helps |
Roof | Wide photos of all roof slopes, valleys, eaves, and penetrations | Shows visible condition before snow and ice |
Gutters | Photos after cleaning, downspouts, extensions, and problem corners | Helps rule out obvious debris-related overflow |
Attic | Insulation, vents, sheathing, old stains, and roof underside | Helps identify heat loss and prior moisture |
Interior ceilings | Rooms below roof edges, exterior walls, and past trouble spots | Creates a baseline before winter stains appear |
Exterior drainage | Downspout discharge areas and grading near foundation | Shows where meltwater is directed |
Maintenance records | Receipts, repair notes, inspection reports, and dated logs | Supports the timeline of care and repairs |
Weather notes | First snow, ice storm, thaw, and date water appears | Connects damage to a specific event |
Do not wait until snow covers the roof. Once winter arrives, the safest views may be blocked, and contractors may be booked for weeks.
What to do if water appears during an ice dam event
If water starts coming in, safety comes first. Water near wiring, fixtures, or outlets can be dangerous. Do not touch wet electrical fixtures. If needed, shut off power to the affected area and call a professional.
Then focus on limiting damage and documenting what happened.
Take photos before cleanup, if it is safe
Capture the condition as you found it:
Active dripping
Ceiling stains
Wet floors or furniture
Ice buildup outside
Snow depth on the roof
Buckets, towels, or temporary protection
Attic moisture, if safely accessible
Take both wide and close photos. Wide shots show location. Close shots show detail.
Stop more damage without making unsafe repairs
Insurance policies often require homeowners to take reasonable steps to prevent further damage. That does not mean climbing onto an icy roof with a shovel.
Reasonable steps may include:
Moving furniture and belongings away from dripping water
Placing buckets or towels under leaks
Calling a roofer, mitigation company, or ice removal professional
Removing snow from the ground with a roof rake, if safe
Keeping receipts for emergency work
Saving damaged materials until the insurer gives guidance, when practical
Avoid chipping ice with sharp tools. That can damage shingles and create new leaks. Steam removal or professional ice dam removal may be safer when the buildup is severe.
Report the claim with a clear timeline
When speaking with an insurer, stick to facts. Provide dates, photos, and records. Avoid guessing at causes beyond what you know.
A clear report might include:
When the snow or ice event occurred
When water was first noticed
Where the water entered or appeared
What steps were taken to reduce damage
What professionals were contacted
Whether similar damage existed before
Keep a claim notebook or digital document. Record names, dates, claim numbers, and instructions.
Repairs that reduce the chance of repeat ice dams
Documentation helps after a loss, but prevention matters more. If the home has a history of ice dams, fall is the time to address the causes.
Common fixes include:
Sealing attic air leaks around pipes, ducts, lights, and wall top plates
Improving attic insulation to reduce heat transfer
Keeping soffit and ridge vents clear
Venting bathroom and kitchen fans outdoors, not into the attic
Repairing damaged flashing
Replacing missing or worn shingles
Installing proper underlayment during roof replacement
Keeping gutters clean and secure
Trimming branches that drop leaves or shade ice-prone areas
Some homes need a building science professional, roofer, or insulation contractor to diagnose the problem correctly. Heat cables may help in specific trouble spots, but they do not fix the heat loss or drainage problems that often feed ice dams.
The best results usually come from reducing warm air escape, improving ventilation, and keeping water moving away from vulnerable edges.
The records worth keeping all winter
Once winter starts, keep the same folder going. A useful winter file includes:
Pre-freeze photos
Receipts for gutter cleaning or roof work
Attic and ceiling baseline photos
Weather notes
Photos after major storms
Emergency mitigation receipts
Contractor reports
Claim correspondence, if any
Photos after repairs are complete
Name files clearly. A photo called `north-bedroom-ceiling-Jan-12` is more useful than a random image number. Store a backup in cloud storage or email the folder to yourself.
Small habits make a difference. After each major storm, take a few exterior photos from the same angles. If a stain appears later, you will have a better record of the roof and ice conditions leading up to it.
A calm October plan can save stress in January
Ice dams turn ordinary winter weather into a roof and water problem. The damage can feel sudden, but the claim often depends on details that existed before the first freeze: roof condition, gutter maintenance, attic ventilation, old stains, and how quickly the homeowner responded.
Before winter settles in, walk the property, photograph the roof and gutters, check the attic if it is safe, and save repair records in one place. If water enters later, document the event, reduce further damage, and report the timeline clearly.
A few dated photos in late October will not stop an ice storm. They can give you a much clearer story if an ice-dam winter arrives.


Comments