


Rhode Island Matching Rule Debate Why Homeowners Still Get Mismatched Roof and Siding Repairs
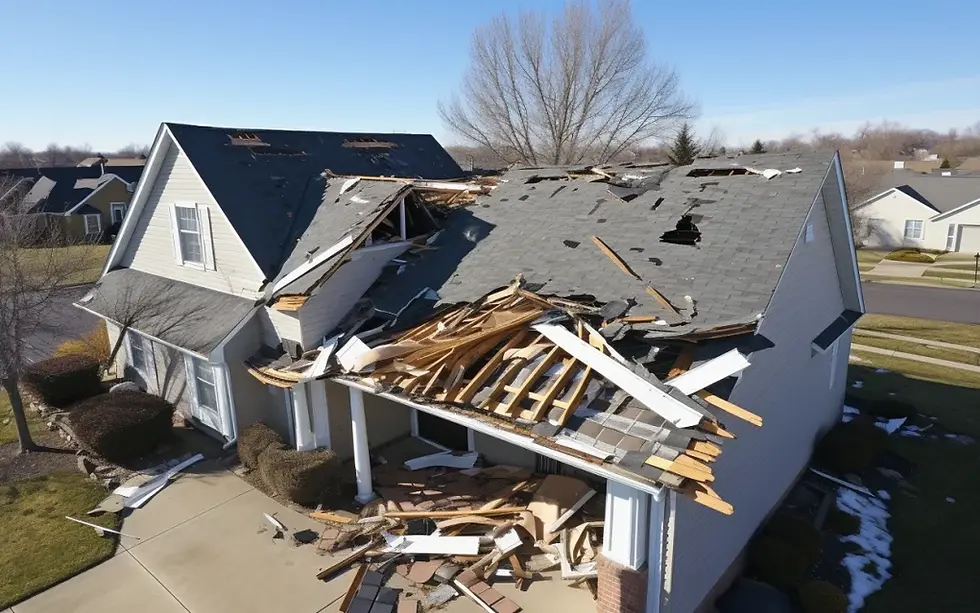
A single windstorm can damage one slope of a roof or one wall of vinyl siding. The insurance estimate may pay to replace only that section. Then the homeowner gets the bad news: the new material does not match the old material, and the house now looks patched.
That is the matching fight in plain English.
This spring, Rhode Island lawmakers considered a bill that would have made it an unfair claims settlement practice for a homeowners insurer to ignore the matching principle when replacement cost coverage applies. On March 31, 2026, the Senate committee recommended holding the bill for further study.
The insurance industry’s response raised the bigger question. The American Property Casualty Insurance Association, or APCIA, argued that Rhode Island regulations already require matching on first-party claims, so the bill would not add new consumer protection.
That sounds simple enough. If matching is already required, no new bill is needed.
But homeowners, contractors, and claim professionals still see partial roof and siding repairs that do not create a reasonably uniform result. So the real question is not just what the rule says. It is why the rule so often fails at the kitchen-table level, where a family is staring at mismatched shingles or two different shades of vinyl siding.
This article is informational only. Insurance coverage and claim rights depend on the policy, the facts, and applicable state law.

What the matching principle is supposed to do
The matching principle is about a practical problem. When an insurer pays for replacement cost repairs, replacing only the physically damaged material may not always restore the property to a reasonably consistent appearance.
That matters most with exterior materials that age, fade, weather, or go out of production.
Common examples include:
Vinyl siding that has faded from sun exposure
Architectural shingles that no longer match the available product line
Aluminum trim with an older finish
Flooring that runs continuously from room to room
Kitchen cabinets or countertops where one damaged section cannot blend in
In a perfect world, matching would be easy. A contractor would find the same product, in the same color, with the same profile, from the same manufacturer. The repair would blend in, and everyone would move on.
Real claims rarely work that cleanly.
Vinyl siding is a good example. Even if the original brand and color are known, the existing siding may have faded for 10 or 15 years. A new panel in the same named color can still stand out. If the product has been discontinued, the difference may be more obvious. The same problem appears on roofs when shingles from a newer production run do not match older shingles that have weathered in place.
The matching principle does not mean every claim automatically turns into a full roof replacement or full siding replacement. It does mean the insurer cannot ignore appearance when replacement cost coverage applies and a partial repair leaves a jarring mismatch.
The hard part is deciding where the line falls.
Why the Rhode Island bill mattered if matching already exists
The industry argument against the Rhode Island bill was direct: state regulations already require matching on first-party claims, so the bill added no meaningful consumer protection.
That answer may satisfy a committee hearing, but it does not answer what many homeowners experience during a claim.
A rule can exist and still be difficult to enforce. A standard can be on the books and still leave too much room for disagreement. A regulation can require matching, yet the first estimate may still pay for the smallest repair the carrier thinks it can justify.
That is why the Rhode Island debate matters. It puts a spotlight on the gap between paper rights and claim outcomes.
If matching is already the law, then homeowners should not regularly end up in fights over obvious mismatches. If insurers already apply matching consistently, then a bill confirming that duty should not create much concern. The pushback itself reveals the tension.
The debate is less about whether the word “matching” exists somewhere in the claim rules. It is more about what happens when:
The adjuster writes for one elevation of siding, but the repair stands out from the street
The roofer cannot source the same shingle, but the estimate pays for a patch
The insurer says the mismatch is “close enough”
The homeowner is told cosmetic differences are not covered
The carrier asks for proof that no reasonable match exists, but gives little guidance on what proof will be accepted
That is where these disputes live.
How mismatched siding claims happen
Vinyl siding claims are one of the most common places matching disputes show up because siding is sold as a system. Color, profile, exposure, texture, and age all matter.
A wind or hail event may damage only one side of a home. The insurer may inspect the property and agree that the damaged panels need replacement. The estimate may include removal and replacement for that wall only.
The problem begins when the contractor tries to buy the material.
The original siding may be discontinued. The color may still exist, but the profile may have changed. The profile may still exist, but the new panel may look brighter because the rest of the siding has faded. Sometimes the only available product is similar in a showroom and clearly different once installed in daylight.
From the homeowner’s point of view, the repair did not restore the home. It created a patch.
From the insurer’s point of view, the damaged material was replaced with something reasonably comparable, and the rest of the siding was not physically damaged.
That disagreement can turn into a matching dispute.
A strong siding matching claim usually needs more than a homeowner saying, “I do not like how it looks.” Better support can include:
Clear photos in natural light from several angles
Manufacturer information showing the original product is discontinued
A supplier letter explaining what materials are available
A contractor statement describing the visible difference
Photos showing the line of sight from the street, driveway, or normal viewing areas
Samples placed next to the existing siding
The phrase reasonably uniform appearance matters because matching is not usually about perfection under a microscope. It is about whether the finished repair looks consistent when viewed in a normal way.
A tiny shade difference on a back wall may be viewed differently from a sharp color break across the front of the home.
Why roof matching is just as difficult
Roof claims create a different version of the same fight. Shingles are exposed to sunlight, weather, algae, and temperature swings. A shingle installed today may not look like the same shingle installed years ago.
Roofing products also change. Manufacturers update colors, rename lines, discontinue styles, or alter granule blends. Even when a product is technically available, the new batch can look different from the old roof once installed.
On a roof, the question is often whether a repair can be made without creating a clear patchwork appearance or damaging surrounding materials.
Some insurers will pay for a slope. Others may pay for a smaller repair area. In some cases, a full roof replacement may be argued if matching cannot be achieved and the roof planes are visible together. But that outcome is never automatic.
The dispute often turns on facts like these:
Whether the damaged shingles can be repaired without breaking surrounding shingles
Whether matching shingles are available
Whether the mismatch is visible from the ground
Whether roof slopes are connected or separated
Whether the policy excludes or limits cosmetic damage
Whether local code affects the repair scope
Roof claims also get complicated because adjusters and roofers may disagree about repairability. An adjuster may believe shingles can be lifted and replaced. A roofer may say the shingles are brittle, sealed, or likely to tear during repair.
That is not only a matching issue. It can also be a workmanship and repair-method issue.

The “close enough” problem
Many matching disputes come down to two words: close enough.
The insurer may say the proposed material is similar. The homeowner may say the finished repair looks wrong. The contractor may say no true match exists. The adjuster may ask for more proof.
Everyone may be looking at the same wall or roof and reaching different conclusions.
That is why vague claim handling creates frustration. Without a clear process, the homeowner may feel trapped between a contractor who says the repair will not match and an insurer who will not expand the scope.
The “close enough” problem also gets worse when the first estimate is treated as final. In reality, the first estimate is often just the opening claim decision based on the information available at that time.
If new information shows the material is discontinued or the proposed repair will not create a uniform appearance, the scope may need to be revisited.
The key is documentation. Matching disputes are won or lost on proof, not irritation.
Why insurers may still write partial repairs
There are several reasons a carrier may write a partial repair even when matching concerns exist.
The first is the basic insurance principle of paying for covered damage. Insurers often start from the position that they owe to repair or replace the damaged property, not undamaged property. If only one roof slope or one siding elevation was hit, the carrier may resist paying for more.
The second is cost control. Matching can expand a claim significantly. One damaged siding wall can become multiple elevations. A partial roof repair can become a full slope or full roof. Insurers watch those costs closely.
The third is ambiguity. Matching rules often use flexible language. Words like reasonable, comparable, continuous, and uniform leave room for interpretation. That makes outcomes less predictable.
The fourth is inconsistent field handling. One adjuster may carefully evaluate line of sight and discontinued materials. Another may rely on a standard estimating template and wait for the homeowner or contractor to challenge it.
That last point is important. Many mismatched repairs happen not because nobody knows matching exists, but because nobody developed the claim file enough before repairs began.
What homeowners should do before accepting a mismatched repair
Once mismatched siding or roofing is installed, the conversation can become harder. The insurer may argue the repair has already been completed. The contractor may not want to remove new materials. The homeowner may have less leverage.
Before accepting a partial repair, take a few basic steps.
Ask the insurer to explain the matching decision in writing.
A written explanation helps identify whether the carrier considered matching at all.
Get product information.
Find the original brand, color, profile, exposure, and age if possible. For roofing, identify the shingle manufacturer and line. For siding, check for markings, invoices, permits, or prior contractor records.
Request supplier confirmation.
If the product is discontinued or unavailable, ask a supplier to put that in writing.
Use samples before installation.
Place the proposed material next to the existing material in daylight. Photograph it from normal viewing distances.
Document line of sight.
Do not only take close-up photos. Show how the repair area looks from the front walk, driveway, yard, or street.
Keep the dispute focused.
The strongest argument is not “I want everything new.” It is “the proposed repair does not restore a reasonably uniform appearance under the replacement cost coverage.”
That framing matters.
Why the Rhode Island debate should not fade away
The Rhode Island bill may have been held for further study, but the issue behind it is not going away.
Homes keep aging. Products keep getting discontinued. Storms keep damaging only part of a roof or part of a siding system. Insurers keep writing estimates based on covered physical damage. Homeowners keep expecting replacement cost coverage to leave the home looking whole.
That conflict will continue whether the rule sits in a regulation, a statute, a claim bulletin, or a court decision.
The APCIA argument that matching is already required in Rhode Island may be technically powerful. It may also be the best reason for homeowners and claim professionals to keep asking harder questions.
If the protection already exists, claim files should show it being applied. Estimates should explain the match analysis. Denials of broader matching scope should cite the facts, not just repeat that only the damaged area is covered. Homeowners should not have to discover the matching principle only after a mismatched repair is installed.
A law that repeats an existing rule may not sound exciting. But sometimes repetition has a purpose. It tells the market that the rule is not optional.
The real test is the finished repair
Matching is not an abstract insurance concept. It shows up every time a house has one bright new siding wall next to three faded walls, or one roof patch that catches the eye from the curb.
The Rhode Island matching rule debate matters because it exposes a simple gap. The standard may already exist, but the result on real homes often falls short.
A fair claim process should answer three practical questions before the work is done:
Can the original material be identified and sourced?
Will the proposed replacement create a reasonably uniform appearance?
If not, what repair scope is needed to restore the property under the policy?
When those questions are handled early, matching disputes become clearer. When they are ignored, homeowners are left fighting over a repair everyone can see does not match.
That is the heart of the issue. If matching is already the rule, it should show up on the house, not just in the claim manual.
Call Alfred Smith CPCU to discuss more. 617 697 2646


Comments