


Why Insurance Companies Refuse Fair Payouts and How to Fight Delay Tactics
An insurance claim can feel simple at first. You paid premiums, something went wrong, and the policy should help cover the loss. Then the adjuster calls with an offer that barely covers repairs. Or the company keeps asking for “one more document.” Weeks pass. Bills pile up. The pressure builds.
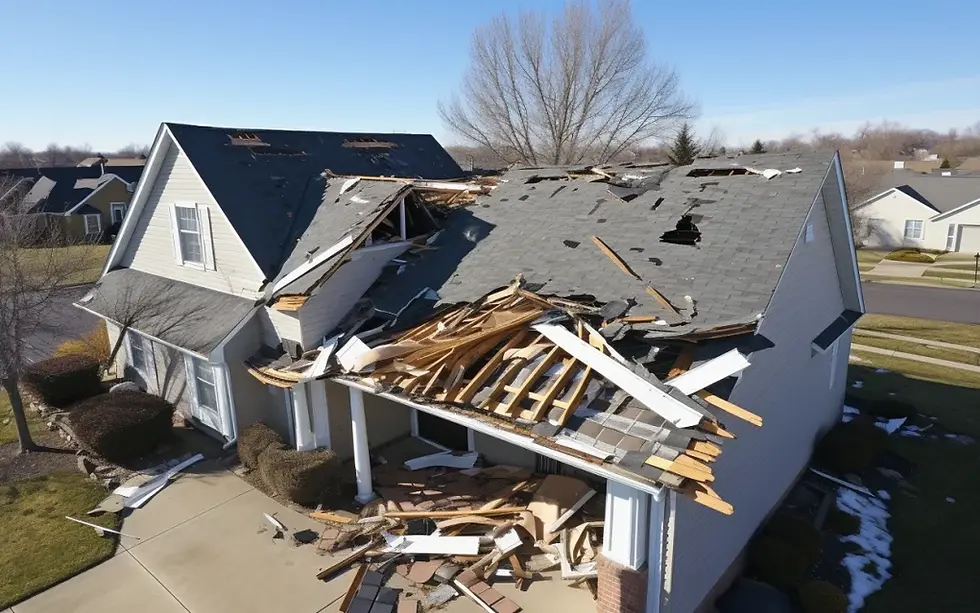
That frustration is common because insurers do not evaluate claims the same way policyholders do. A homeowner, driver, or injured person sees damage, disruption, and cost. The insurance company sees policy language, claim reserves, repair estimates, exclusions, depreciation, liability arguments, and profit pressure.
This does not mean every insurer acts in bad faith. It does mean you should treat a claim like a serious financial matter. The stronger your records, the harder it becomes for the company to ignore the facts.
This article is informational only and is not legal advice. Insurance rules vary by state, policy, and claim type.

Insurers often make low offers because the claim file favors them at first
Insurance companies handle claims all day. Most policyholders handle one only after a crash, fire, storm, leak, theft, or injury. That imbalance matters.
The first offer is often based on the insurer’s version of the facts. That may include a short inspection, photos taken by an adjuster, software-generated repair estimates, preferred vendor pricing, or a narrow reading of the policy. If the file does not include your evidence yet, the number may come in low.
Insurers may also discount a claim because they see uncertainty. If the cause of damage is unclear, the injury records are incomplete, or repair estimates conflict, the company may use that uncertainty to justify a smaller payment.
Common reasons for a low payout include:
Depreciation
The insurer may reduce payment for age, wear, or prior condition, especially in property claims.
Disputed cause
The company may argue that the policy does not cover the event that caused the loss.
Partial damage estimates
An estimate may include visible repairs but leave out hidden damage, code upgrades, matching materials, or related costs.
Policy limits and exclusions
The company may point to limits, deductibles, exclusions, endorsements, or special caps.
Comparative fault
In auto or injury claims, the insurer may argue that someone else caused part of the loss, including you.
Medical necessity disputes
Injury claims can be reduced if the insurer questions treatment, timing, or whether care was related to the event.
A low offer is not always the final answer. It is often the start of negotiation. The mistake is treating it like a verdict.
Delay tactics work because time creates pressure
Delay is one of the most effective tools in a claim dispute. The longer a claim drags on, the more likely a person is to accept less just to move forward.
Delays may look polite and procedural. An adjuster may say the file is under review, a supervisor needs to approve payment, another inspection is required, or a missing form is holding things up. Some delays are legitimate. Claims can involve complex facts, multiple parties, and coverage analysis.
But repeated delays without clear reasons deserve attention.
Watch for these patterns:
The insurer keeps requesting documents you already sent.
The adjuster stops responding after you challenge the offer.
The company changes adjusters several times.
Inspections are scheduled, canceled, and rescheduled.
Payment is approved verbally but never arrives.
The insurer asks broad questions that seem unrelated to the claim.
The company waits until deadlines are near before asking for more information.
The adjuster will not explain the basis for the denial or low offer in writing.
Delay tactics can also appear as silence. A week of silence may be normal. Several weeks with no update, after you have provided requested information, is different.
A claim moves faster when every request, response, estimate, and deadline is written down.
Do not rely on memory. Build a paper trail early.

Start by reading the policy like a rulebook
Many claim disputes turn on language buried inside the policy. The declarations page gives a summary, but the full policy controls the details.
Look for these sections:
Covered losses
This explains what events may be covered.
Exclusions
This lists what the company may refuse to cover.
Duties after loss
This tells you what you must do after a claim, such as giving notice, protecting property, or cooperating with the investigation.
Special limits
Some categories have lower caps than the overall policy limit.
Replacement cost and actual cash value
Replacement cost usually concerns the cost to replace damaged property. Actual cash value often includes depreciation.
Appraisal or dispute procedures
Some property policies include a process for resolving disputes over the amount of loss.
Deadlines
Policies and state laws may set time limits for notice, proof of loss, lawsuits, appeals, or supplemental claims.
If you do not understand a term, ask the adjuster to identify the exact policy language they rely on. Ask for the page, section, and wording. A vague answer like “that is not covered” is not enough.
A useful response is simple:
“I understand your position. Please send the policy language and factual basis you are relying on for that decision.”
That sentence does two things. It keeps the tone professional, and it forces the dispute into writing.
Build evidence before you argue numbers
A strong claim is not built on anger. It is built on proof.
Start with a claim folder. It can be digital, physical, or both. Keep everything in one place so you can respond quickly and spot inconsistencies.
Include:
Photos and videos from different angles
Date-stamped images if available
Repair estimates from independent contractors
Receipts for temporary repairs, hotels, rentals, towing, storage, or medical copays
Police reports, fire reports, incident reports, or weather records when relevant
Medical records and bills for injury claims
Names and contact information for witnesses
Emails, letters, and text messages with the insurer
A call log with dates, times, names, and summaries
Copies of every form you send
For property damage, photograph before cleanup if it is safe. Then photograph temporary repairs. Save damaged materials when reasonable. If a pipe burst, roof leak, or fire caused the loss, do not throw away key evidence too quickly.
For vehicle claims, compare the insurer’s estimate with a repair shop estimate. Ask the shop to identify missed items, parts issues, labor differences, calibration needs, and hidden damage.
For injury claims, gaps in treatment can become a major dispute. If treatment stopped because of cost, scheduling, transportation, or another reason, make sure the records explain it accurately.
The goal is not to overwhelm the adjuster. The goal is to make the correct payment easier to justify than the low offer.
Respond to a low offer with a clear written demand
Do not reject a low offer with only a phone call. Put your response in writing.
A good claim response should be calm, specific, and supported by documents. It should not read like a rant. It should give the insurer a clear path to reassess the claim.
Your written response can include:
The claim number
The date of loss
A short summary of what happened
The amount offered
Why the offer is too low
The amount you believe is supported
A list of attached evidence
A request for a written response by a reasonable date
For example:
“Based on the attached contractor estimate, photos, and receipts, the current payment does not include drying work, damaged flooring in the adjoining room, baseboard replacement, or required painting for a consistent repair. Please review the attached materials and provide a revised estimate or a written explanation of any disputed item.”
Be precise. If the insurer missed $4,800 in repairs, identify the line items. If the offer ignores medical bills, list the bills and dates. If the company applied depreciation, ask how it calculated that amount.
When possible, compare documents side by side. The insurer’s estimate may include 200 square feet of flooring while the contractor measured 350. That kind of specific difference is harder to dismiss.
Push back on delay without sounding unreasonable
A professional tone helps, but patience does not mean silence. If the company delays, create a written record that shows you cooperated and asked for updates.
Use short messages like:
“Please confirm whether you need any additional documents to complete your review.”
“Please provide the current status of the claim and the reason payment has not been issued.”
“Please identify the remaining investigation steps and the expected date for a decision.”
“Please confirm receipt of the documents sent on March 4.”
Give reasonable deadlines. For many routine updates, five to seven business days is a fair request. If the matter is urgent, explain why. For example, a home may be unsafe, a rental car may expire, or a contractor may be waiting to start repairs.
Keep a claim diary. After each phone call, write down:
Date and time
Person you spoke with
Phone number or email
What was discussed
Any promises made
Any deadline mentioned
Then send a short follow-up email:
“Thank you for speaking with me today. My understanding is that you will review the contractor estimate and respond by Friday. Please let me know if I misunderstood.”
That message can matter later if the insurer denies making a promise.
Know the difference between a tough claim and bad faith
Not every dispute is bad faith. Insurance companies can investigate claims, question amounts, request records, and deny losses that the policy does not cover.
Bad faith generally means the insurer handled the claim unfairly or unreasonably under the law. The exact standard varies by state.
Possible warning signs include:
Denying a claim without a reasonable investigation
Refusing to explain the policy basis for denial
Ignoring strong evidence
Misrepresenting policy language
Delaying payment after coverage is clear
Offering far less than the documented value without support
Pressuring a person to settle before the full damage is known
If you suspect bad faith, do not make accusations casually. Focus on facts. Ask the insurer to explain its position in writing. Gather the timeline. Save every message.
A clear record is more useful than angry language.
Escalate when the adjuster will not move the claim forward
If the front-line adjuster is not responding or refuses to address evidence, escalation may help.
Start within the company. Ask for a supervisor or claim manager. Send a concise summary of the issue and attach key documents. Do not send everything at once unless requested. Lead with the strongest evidence.
If that fails, consider outside options.
File a complaint with your state insurance department
Each state has an insurance regulator. These departments usually accept consumer complaints about claim handling, delays, denials, and communication problems.
A complaint does not guarantee payment. It can force the insurer to respond and explain its position. Keep the complaint factual. Include the claim number, dates, documents sent, and the specific problem.
Use the appraisal process if the policy allows it
Many property policies include appraisal for disputes over the amount of loss. Appraisal usually does not decide whether damage is covered. It focuses on value.
This process can be useful when the insurer agrees there is covered damage but disputes the cost to repair or replace it. Read the policy carefully before demanding appraisal, because the process can involve fees and specific steps.
Hire a public adjuster for property claims
A public adjuster works for the policyholder, not the insurance company. Public adjusters often help document property damage, prepare estimates, and negotiate with the insurer.
They usually charge a percentage of the recovery. Before hiring one, check licensing rules in your state, read the contract, and understand the fee.
Talk to an attorney when the stakes are high
Legal help may make sense if the claim involves serious injuries, a large property loss, a denied claim, suspected bad faith, or a deadline to sue. Many insurance dispute attorneys offer consultations. Fee structures vary.
Bring the policy, denial letters, estimates, medical records, photos, and your claim diary. The better organized the file, the easier it is to evaluate.

Avoid mistakes that make the insurer’s job easier
Some claim problems come from the company. Others come from avoidable missteps.
Try to avoid these:
Waiting too long to report the claim
Late notice can create coverage problems.
Making permanent repairs before documentation
Protect the property, but photograph damage first when safe.
Giving recorded statements without preparation
Be truthful, but do not guess. If you do not know, say so.
Signing broad releases too early
A release may end the claim, including unknown or future damages.
Accepting a check without understanding it
Some payments are partial. Others may be tied to settlement language. Read any accompanying letter.
Exaggerating
Inflated claims damage credibility and can create serious consequences.
Communicating only by phone
Calls are useful, but written records protect you.
Missing deadlines
Calendar every date in the policy and every date the insurer gives you.
The strongest position is honest, documented, and persistent.
A fair payout usually requires proof, pressure, and patience
Insurance companies refuse fair payouts for many reasons. Some involve real policy disputes. Some involve incomplete evidence. Some involve delay tactics that wear people down. The response should be the same in every case: get organized, ask for the basis in writing, support your number with evidence, and escalate when the company will not act reasonably.
Do not let the insurer control the whole claim file. Build your own.
At minimum, keep a diary, save every document, compare estimates, challenge vague explanations, and track deadlines. If the money at stake is significant, get qualified help before signing anything final.
A claim is easier to undervalue when the policyholder is tired, scattered, or silent. A well-documented claim is much harder to ignore.
Any questions or need of discussion please call me for a free consult.
Alfred Smith CPCU
Alfred Smith CPCU Claims Services
617 697 2646


Comments